In 2024 a removal credit sold for 381 percent more than a reduction credit, up from a 245 percent premium the year before, according to Ecosystem Marketplace's State of the Voluntary Carbon Market 2025. Both instruments represent one tonne of CO2 equivalent. Both are issued by the same registries and retired the same way. So the avoidance vs removal carbon credits question is really a question about why the market prices the same unit so differently, and whether that gap will hold. The short answer: the gap is a claim premium, not a quality premium, and the rules that create it are getting stricter, not looser.
The definition, and why it stops short
A carbon credit is a tradable instrument that conveys a claim to avoided greenhouse gas emissions or to the enhanced removal of greenhouse gases from the atmosphere, typically denominated as one metric tonne of CO2 equivalent, which the buyer retires to count toward a mitigation goal. That single sentence already contains the split.
Avoidance credits, also called reduction credits, pay for emissions that would otherwise have happened. The Oxford Principles group them into three kinds: reducing fossil emissions, for example by replacing fossil fuels with renewables; protecting ecosystems, soils and vegetation from damage; and capturing fossil carbon before it reaches the air. Removal credits pay for human activity that takes CO2 out of the atmosphere and durably stores it in geological, land or ocean reservoirs or in products, and natural uptake that would have happened anyway does not count.
Every explainer on the first page of Google stops here. The definition is correct, and it tells you nothing about why a buyer in Munich pays twenty-five times more for a biochar tonne than for a REDD+ tonne. For that you need the price tiers and the claim rules, in that order.
Three price tiers, not two
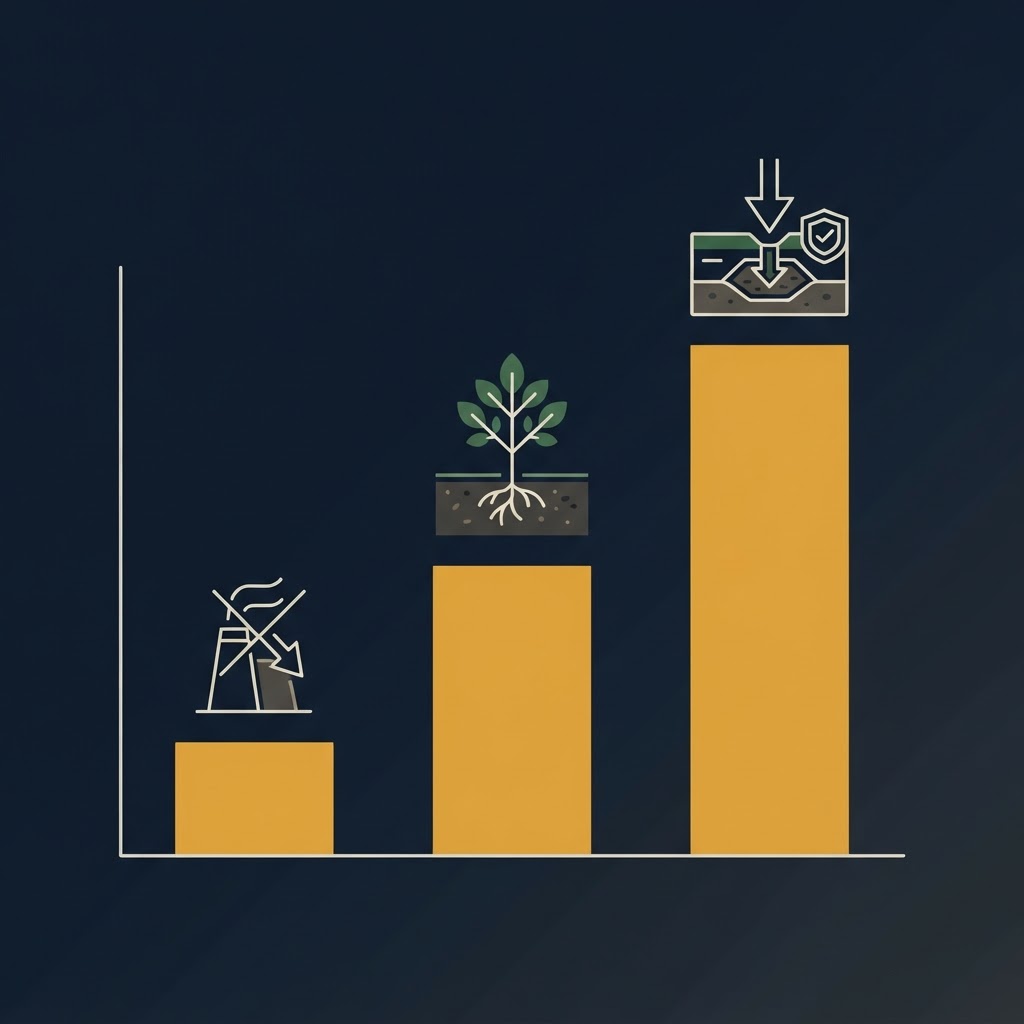
The avoidance vs removal split is usually drawn as two columns. The market actually trades in three bands, and the third is where the real money is.
Tier 1: avoidance
Ecosystem Marketplace's transaction survey puts the 2024 average at 4.05 dollars per tonne for reduction credits against 19.50 dollars for removals, on volumes of 38.8 million tonnes avoidance and 4.2 million tonnes removal, with a further 22.8 million tonnes from projects that represent both. Only 5 percent of credits traded in 2024 originated from removal project types. Live order books in 2026 say the same thing: the Emsurge price assessment for July 2026 shows average asks of 4.85 dollars for REDD+, 5.31 dollars for cookstoves and 7.30 dollars for CCP-labelled supply.
Tier 2: nature-based removal
Afforestation, reforestation and agroforestry are removals and they carry the bulk of the removal premium. The same July 2026 order book shows an average ARR ask of 16 dollars per tonne and blue carbon at 37.46 dollars. Quality is now priced inside this tier too. Sylvera's 2025 data shows BBB-rated and better ARR credits averaging around 26 dollars a tonne by late 2025 against roughly 14 dollars for lower-rated supply, with those two prices closely aligned at the start of the year.
Tier 3: durable removal
This is the band that explains the headline. Puro.earth's Nasdaq index put the composite CORC price at 134.27 euros and the biochar index at 124.02 euros per tonne in September 2026. Emsurge's biochar and tech CDR line sat at 121.17 dollars. The LSE Grantham Institute's deal dataset shows the method means: biochar at 184.40 dollars per tonne, BECCS at 329.43 dollars and DACCS at 1,000.96 dollars, against an EU ETS allowance price of around 84 dollars and a UK ETS price of 66 dollars.
Set the three tiers side by side and the picture is not a 5x gap. It is a 4x gap between avoidance and nature-based removal, then another 6x to 8x between nature-based removal and durable removal. The variable that separates tier 2 from tier 3 is durability, and durability is where the standards do their work. The vocabulary matters here, and we unpacked the credit versus offset distinction separately in carbon credits vs carbon offsets.
The gap is a claim premium, not a quality premium
The most common explanation for the price gap is that removals are higher quality. The rating evidence does not support that.
What a rating agency actually finds
Calyx Global, which rates individual projects for greenhouse gas integrity, published its own data on exactly this question and concluded that there is little difference in the quality of avoidance versus removal-based credits, that many afforestation credits are not additional because they come from large-scale monoculture timber plantations in regions where such operations are common practice, and that it would be much better for the planet to purchase an A-rated avoidance credit over an E-rated removal credit. A removal tonne can be badly measured. An avoidance tonne can be rigorously measured. Integrity is a project property, not a category property, and how carbon credits are verified is the same MRV chain for both.
So if quality is not the mechanism, what is?
What SBTi lets you say with each credit
The mechanism is the claim. Under the SBTi Corporate Net-Zero Standard V2, published in June 2026, companies must at their net-zero target year reduce scope 1, 2 and 3 emissions to residual levels and neutralize all residual emissions using eligible carbon removals, and from 2035 Category A companies shall support eligible carbon removals equal to at least 1 percent of ongoing scope 1, 2 and 3 emissions, including a defined and increasing share of long-lived removals. Avoidance credits are not on that list. They can be part of a voluntary ongoing emissions responsibility programme. They cannot neutralize a residual tonne.
The durability rule tightens the funnel further. In the SBTi's basis for conclusions, the drafters explain that long-lived greenhouse gases such as fossil CO2 are to be neutralized with removals capable of retaining carbon for centuries to millennia, and that a consulted portfolio approach allowing 59 percent of residuals to be covered by short-lived removals was dropped after expert groups and external legal counsel warned it would let fossil CO2 be neutralized by short-lived storage, creating greenwashing and litigation risk.
Reporting rules say the same thing from the disclosure side. For a DACH company under CSRD, a CORC represents one tonne of CO2 removed and stored for at least 100 years, issued ex-post only after third-party verification, and it cannot be netted against scope 1 to 3 emissions under CSRD or SBTi rules; it belongs in a separate neutralisation or beyond-value-chain disclosure, with over one million CORCs issued since 2019 across tiers labelled CORC100+, CORC200+ and CORC1000+.
Put together, the three bands map onto three claims. An avoidance credit buys a contribution claim. A nature-based removal credit buys a neutralization claim with reversal risk attached. A durable removal credit buys the only neutralization claim that survives the like-for-like test for fossil emissions. Buyers are not paying for better carbon. They are paying for a sentence they are allowed to put in an audited report.
Why the gap is not closing
A claim premium created by standards should narrow as supply responds. Three datasets say it is not responding fast.
Spot and forward markets have already decoupled. Sylvera counted 168 million credits retired in 2025 for 1.04 billion dollars, a weighted average of 6.10 dollars, while offtake deals announced that year totalled 12.3 billion dollars and will deliver only around 12 million credits a year through 2035 at a weighted average price of 180 dollars. Less than 10 percent of today's retirement volume is carrying twice the market's annual value.
Delivery lags contracts. The LSE dataset finds that by the end of 2025 only 1.2 percent of contracted durable removal had actually been delivered, and that expected learning rates for most methods are very low or negative, which the authors read as structural bottlenecks rather than an immature technology working down a cost curve. Senken's price corridor makes the comparison explicit: across 43 million tonnes of contracted removal, durable methods show a learning rate of 1 percent per doubling of capacity where solar managed 20 percent, so the gap between a durable and a nature-based tonne narrows from 3.6x to 2.0x by 2040 and does not close.
Buyers and suppliers still disagree on the number. The CDR.fyi and OPIS survey for 2026 found the average price spread between durable removal buyers and suppliers narrowed from 107 to 98 dollars per tonne, with respondents expecting 48 dollars by 2030, and concluded that durable removal credits are unlikely to broadly reach 100 dollars per tonne by 2030. On biochar specifically, suppliers say they need 187 dollars per tonne in 2025 for a reasonable profit while buyers consider 155 dollars expensive, and 77 percent of buyers rank price as a top factor in supplier selection.
One demand-side caveat belongs here. The durable market is still a handful of corporate buyers, and Emsurge's July 2026 note records Microsoft cutting its durable removal buying by around 80 percent. The claim rules create the floor under prices. The thinness of the buyer base is what makes them volatile above it. Whether the gap is worth paying is a buyer's question we take up in cost of carbon removal credits.
What this means if you produce the tonne
Most pages on this topic are written for buyers. Energaia sits on the other side of the trade. Our process is to collect local biomass or sewage sludge, gasify it at high temperature to clean syngas, convert the gas to dispatchable electricity and heat, and capture biochar plus verified CO2 offsets, all run on site. The carbon credit is a by-product of a plant that was built to turn a disposal cost into power, which changes how the avoidance vs removal split looks from the producer's seat.
A waste-to-energy plant can in principle generate both credit types. Displacing diesel generation in a Nigerian industrial park is avoidance. Stabilising the carbon in biochar and putting it in soil or concrete is removal. The same feedstock, the same site, two very different revenue lines, and the data above says the second is worth an order of magnitude more per tonne.
Biochar is a specific case within durable removal for four reasons that the LSE and Senken datasets make concrete. It is one of only three methods the EU recognises as permanent under the CRCF, alongside DACCS and BioCCS, and we covered what that certification demands of a plant in CRCF permanent carbon removal credits. It is the only durable method whose credits are actively traded today, with 748 deals in the LSE sample and 79 percent of them offtake agreements. Its build cycle is short: a biochar plant issues its first credit in 12 to 24 months where a new forest needs five to ten years. And its price is policy-linked in a way no other removal is: a 1 percent rise in the EU ETS allowance price lifts biochar credit prices by 0.39 percent, because the two markets share buyers.
The producer-side risks are also specific. Multi-year biochar contracts recently cleared at 80 to 120 dollars against a 140 dollar spot price, and forward curves sit below spot. The supplier breakeven figures that CDR.fyi collects, 143 dollars for biochar against 232 for BECCS and 670 for direct air capture, only hold if the plant's heat and power are sold too, which is why Energaia's carbon credit management service covers project certification, trading strategy and MRV as one package next to the feasibility study and the gasification system itself. The mechanics from pyrolysis to issued tonne are in how biochar carbon credits work, and the live benchmarks in biochar carbon credit price per ton. How long the carbon actually stays put is its own question, answered in how long biochar stores carbon.
Decision table: which credit for which claim
| Claim you want to make | Credit type | Price band, 2024 to 2026 | Rule that governs it |
|---|---|---|---|
| Contribution beyond the value chain | Avoidance or any removal | 4 to 7 USD per tonne | SBTi optional ongoing emissions responsibility |
| Neutralize residual emissions at net zero | Eligible removal | 16 to 40 USD nature-based | SBTi CNZS V2 chapter 6 |
| Neutralize residual fossil CO2 | Long-lived removal, 100 plus years | 120 to 330 USD biochar and BECCS | SBTi like-for-like durability, EU CRCF |
| Meet the 2035 SBTi removal floor | Eligible removal, rising share long-lived | Blended, contract dependent | SBTi post-2035 responsibility requirement |
Three checks before signing, whichever row you are in. First, the retirement must be in your name on a public registry, or the claim is not yours. Second, the durability tier must match the emission you are neutralizing, so a CORC100+ for a fossil residual and not a ten-year soil credit. Third, prefer ex-post issuance to ex-ante promises, because the 1.2 percent delivery ratio above is a contract statistic, not a registry one. The buyer's checklist for the biochar case specifically is in are biochar carbon credits reliable.
FAQ
Are removal credits higher quality than avoidance credits? Not by rating evidence. Calyx Global's project ratings show little difference in greenhouse gas integrity between the two categories, and some afforestation removal credits rate poorly on additionality. The premium comes from what the credit lets you claim under net-zero standards, not from the carbon accounting being better.
Can avoidance credits count toward an SBTi net-zero target? Not for neutralizing residual emissions. The Corporate Net-Zero Standard V2 requires eligible carbon removals for that purpose, and from 2035 requires Category A companies to support removals equal to at least 1 percent of ongoing emissions. Avoidance credits can be recognised under the optional ongoing emissions responsibility programme.
Is tree planting an avoidance or a removal credit? Removal, because growing trees take CO2 out of the air. Protecting an existing forest from deforestation is avoidance. The planted forest carries reversal risk from fire, pests and land-use change, which is why standards treat it as short-lived storage rather than the century-scale storage required for fossil residuals.
Why are biochar credits cheaper than direct air capture credits? Biochar runs on pyrolysis plants that also sell heat and power, uses biomass that is already collected, and reaches its first credit in one to two years. Direct air capture is energy-intensive and capital-heavy. In the LSE deal dataset the mean biochar price is 184 dollars per tonne against 1,001 dollars for direct air capture with storage.
Will removal credits get cheaper? Slowly at best. Durable removal shows a learning rate of about 1 percent per doubling of capacity, suppliers report structural cost floors, and the 2026 CDR.fyi survey concludes that durable credits are unlikely to broadly reach 100 dollars per tonne by 2030. Multi-year contracts already clear below spot for biochar, so the realistic path is flatter forward prices rather than a collapse.